Charitable Trust Decision Helper
Answer the questions below to see which type of charitable trust structure might best fit your financial and personal goals.
Your Recommendation
Key Considerations Based on Your Answers:
You’re staring at a pile of paperwork, pen hovering over the dotted line. The goal is noble: you want to leave a legacy, support a cause close to your heart, and maybe save a few quid on taxes along the way. But then the question hits you like a brick through a window: is a charitable trust revocable or irrevocable?
Here’s the short answer that might surprise you: it depends entirely on what you want to achieve. Most people assume all charitable trusts are set in stone, but that’s not strictly true. In fact, the distinction between revocable and irrevocable is the single most important decision you’ll make when setting one up. It dictates whether you can change your mind later, how much control you keep, and-crucially-how the taxman treats your donation.
The Core Difference: Control vs. Commitment
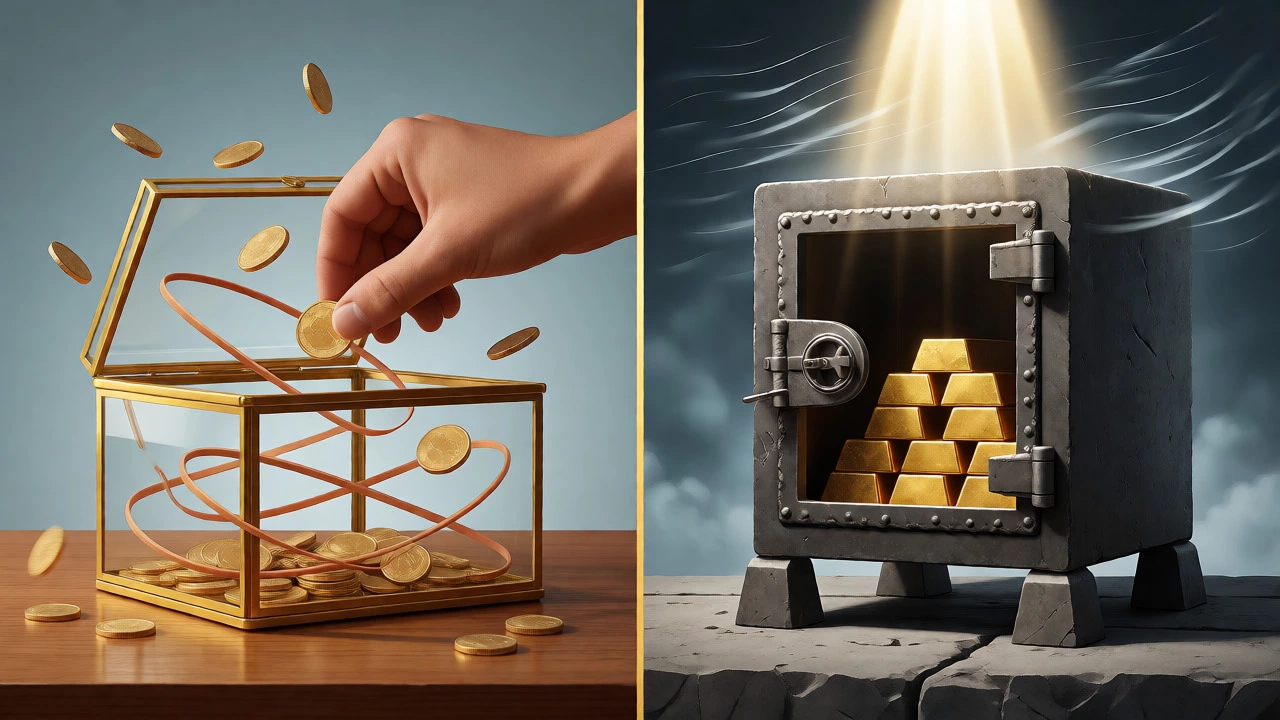
Think of a trust as a box where you put your assets. If the box has a lid you can open anytime, it’s revocable. If the lid is welded shut, it’s irrevocable. When we talk about a charitable trust, we’re talking about a legal arrangement designed specifically to benefit a charity or the public good, rather than just family members.
A revocable charitable trust allows you to retain full control. You can change the beneficiaries, alter the terms, or even dissolve the trust completely if life throws you a curveball. Maybe you lose your job, or perhaps the charity you picked suddenly changes its mission statement in a way you dislike. With a revocable structure, you have an escape hatch.
On the flip side, an irrevocable charitable trust locks those assets away. Once you transfer money or property into this trust, it no longer belongs to you. It belongs to the trust itself, managed by trustees for the benefit of the charity. You generally cannot take it back, change the rules, or undo the deal without complex legal procedures (and sometimes court approval).
| Feature | Revocable Trust | Irrevocable Trust |
|---|---|---|
| Control | High. You can modify or cancel. | Low. Assets are permanently transferred. |
| Tax Deductions | None upon creation. Deductions occur only when distributions are made. | Immediate income tax deduction based on present value of future gifts. |
| Estate Tax | Assets remain in your taxable estate. | Assets are removed from your taxable estate. |
| Creditor Protection | Minimal. Creditors can often reach these assets. | Strong. Assets are shielded from most creditors. |
| Flexibility | Very high. | Very low. |
Why Most People Choose Irrevocable
If flexibility sounds nice, why do so many wealthy donors opt for the rigid structure of an irrevocable trust? The answer usually comes down to two words: tax efficiency.
When you fund an irrevocable charitable remainder trust (CRT) or a charitable lead trust (CLT), you’re making a permanent gift. Because you’ve given up control, the IRS (or HMRC, depending on where you live) views this as a completed gift. This means you can claim a significant income tax deduction in the year you fund the trust. You don’t have to wait until the charity actually receives the cash years later; you get the credit now, based on the actuarial value of the future payments.
Furthermore, moving assets out of your name removes them from your estate. For individuals with substantial wealth, this can mean saving hundreds of thousands in inheritance or estate taxes. If you hold highly appreciated stock, placing it in an irrevocable trust also allows the trustee to sell those shares without triggering capital gains tax immediately, letting the full amount go to work for the charity.
When Revocable Makes Sense
So, is the revocable option useless? Not at all. It serves a specific purpose, particularly for those who aren’t ready to let go completely.
Imagine you want to support a local food bank but you’re worried about your own retirement security. You might set up a revocable living trust that names the food bank as a beneficiary upon your death. During your lifetime, you can spend the assets freely. If you need that money for medical bills or home repairs, you can tap into it. The charity gets nothing until you pass away, but you get the peace of mind that your legacy is planned.
This approach is common in basic estate planning. It’s less about immediate tax breaks and more about ensuring your wishes are carried out after you’re gone, while keeping your hands on the steering wheel today. It’s safer, simpler, and requires less upfront commitment.
The Legal Reality: Can You Change Your Mind?
Let’s dig into the mechanics. If you create an irrevocable trust, can you ever get the money back? Technically, yes, but it’s difficult. You might need the consent of the charity and the trustees, or you might need to prove that circumstances have changed drastically enough to warrant modification under doctrines like cypres (a legal principle allowing courts to redirect charitable funds if the original purpose becomes impossible).
In contrast, a revocable trust is easy to amend. You sign a new document, update the terms, and you’re done. No lawyers needed for every minor tweak. However, remember that because you haven’t truly “given” the assets away, you don’t get the immediate tax write-off. You only get deductions when the trust actually distributes income to the charity.
Common Pitfalls to Avoid
One major mistake people make is assuming they can treat an irrevocable trust like a savings account. You can’t just withdraw funds for a holiday in Spain. Once the assets are in, they’re dedicated to the charitable purpose defined in the trust deed. If you need liquidity, you must plan for that outside the trust.
Another trap is choosing the wrong type of charitable vehicle. There are several structures:
- Charitable Remainder Trust (CRT): You get income for a period, then the charity gets the rest. Usually irrevocable.
- Charitable Lead Trust (CLT): The charity gets income first, then your heirs get the remaining assets. Can be structured variously.
- Donor-Advised Fund (DAF): Often confused with trusts. A DAF is irrevocable once funded, but you retain advisory rights on where grants go. It’s a middle ground many find appealing.
Make sure you understand which structure you’re buying into. A DAF isn’t technically a trust in the same legal sense, but it functions similarly for many donors. Always clarify the legal definition with your advisor.
How to Decide: A Simple Checklist
Still unsure? Run through this quick mental test:
- Do you need the money back soon? If there’s a chance you’ll need access to the principal within 5-10 years, lean toward revocable or a Donor-Advised Fund.
- Are you looking for big tax breaks now? If you have a high-income year and want to offset taxes, an irrevocable CRT or CLT is likely better.
- Is your estate large enough to worry about inheritance tax? If yes, removing assets via an irrevocable trust is a powerful strategy.
- Do you trust the charity’s long-term stability? Since irrevocable gifts are permanent, ensure the organization is solid. Revocable arrangements give you a chance to pivot if things go south.
Ultimately, the choice between revocable and irrevocable isn’t just about law; it’s about your personal financial picture and your appetite for risk. There’s no universal right answer, only the right answer for your situation.
Can I change the beneficiary of an irrevocable charitable trust?
Generally, no. Once established, the beneficiary is fixed. However, some trusts include a "power of appointment" clause that allows the donor to change the beneficiary among a pre-selected group of charities. Without such a clause, changing the beneficiary typically requires court approval or the consent of all parties involved, including the charity.
Do I get a tax deduction for funding a revocable charitable trust?
Not immediately. Because you retain control over the assets, the IRS does not consider the gift complete until the trust actually distributes money to the charity. You will receive tax deductions only when those distributions occur, not when you initially fund the trust.
What happens if the charity dissolves?
Most well-drafted charitable trusts include a "successor beneficiary" clause. This names alternative charities to receive the funds if the primary beneficiary ceases to exist or loses its tax-exempt status. If no successor is named, a court may apply the cy pres doctrine to direct funds to a similar charitable purpose.
Is a Donor-Advised Fund considered a charitable trust?
Legally, a Donor-Advised Fund (DAF) is usually a grantmaking program sponsored by a public charity, not a separate legal entity like a private foundation or a standalone trust. However, functionally, it operates very similarly to an irrevocable charitable trust: you donate assets, get an immediate tax deduction, and recommend grants to other charities, though the sponsoring organization retains final authority.
Can creditors seize assets in an irrevocable charitable trust?
Usually, no. Because the assets are no longer owned by you, they are generally protected from your personal creditors. However, if you transferred assets into the trust shortly before filing for bankruptcy or while already insolvent, creditors might challenge the transfer as fraudulent conveyance.